Written Commentary

While difficult to find anything supportive in today’s USDA data the soybean complex rebounded sharply (led by meal) in the last hour of trade to close moderately higher. Corn briefly traded down its daily limit of $.30 bu. however, bounced to close well off session lows. The market needs to find a price level that stimulates better demand.
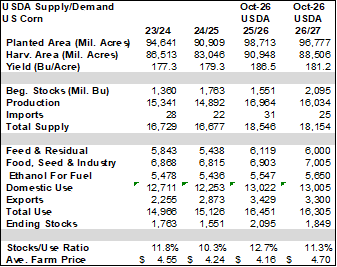
Corn: Higher yields in the WCB only make sense if harvested acres are lowered with more acres cut for silage or abandoned as failed, something that will be closely monitored in future reports. We’ll likely need to see Chinese interest in US corn for price to climb back above $5.00 bu.
Nov-26 beans fell to a 6-week low before recovering to close $.04 ½ higher. Dec-26 meal was up $8 per ton at $365.60 while Dec-26 oil was up 10 points at 68.02. Crush margins jumped to a 2-month high, up $.14 to $2.60 ½ bu. with meal PV reaching 51.8%. I suspect it will be difficult for US production to go much higher with record yields already being forecast. Prices will continue to be sensitive to the pace of Chinese purchases with an increased focus on SA weather and growing conditions. Hurricane Isaias is expected to make landfall near the Florida/Alabama border tonight as a Category 2 or 3 storm. Damaging winds and coastal flooding are expected while minimal impact on Gulf export operations. Harvest activity in the SE and ECB will be delayed while crop damage will likely be limited to cotton in AL/GA.
No major surprises in today’s data to impact wheat a whole lot. US stocks were slightly above expectations due to lower exports but probably overdue for a reduction. Black Sea headlines will continue to drive prices while improved moisture in the US southern plains will work to limit rally attempts. No major data from the USDA on wheat until the Jan-27 report on production, stocks and 2027 winter acres.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.