Written Commentary

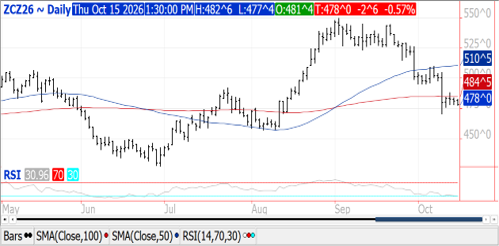
Prices were $.03-$.04 lower, closing near session lows, however spreads firmed in choppy, 2-sided trade. Initial support for Dec-26 futures is at last week’s low near $4.70, followed by the August low at $4.57 ¼. Conab is projecting Brazil’s 2026/27 production at 148 mmt, up from 144 mmt in 2025/26. 1st crop production is est. at 32.1 mmt (29.5 YA) with 2nd crop production at 113.26 mmt (112.1 YA). A small 3rd crop rounds out the total. The current USDA production forecast for 26/27 is 139 mmt. Expana lowered their EU corn production forecast another 1.3 mmt to 44.9 mmt, which if realized would be the lowest since 1990. Last week the USDA lowered their forecast 2 mmt to 48 mmt. EIA data showed ethanol production increased to 313 mil. gallons last week, up from 310 mil. the previous week while down 1% YOY. There was 104.5 mil. bu. of corn used in the production process, or 14.9 mil. bu. per day, well below the 15.6 needed to reach the revised USDA corn usage estimate of 5.650 bil. bu. In the MY to date there has been 577 mil. bu. used, or 14.8 mbd, an annualized pace of 5.402 bil. bu. Stocks rose to 23.9 mil. barrels, well above the 22.6 mb from YA. Tomorrow’s export sales are expected to range from 25-50 mil. bu. Until we see improved demand, the path of least resistance for corn is lower as speculators shed length while US farmers harvest a better-than-expected crop, at least according to the USDA.
Prices across the complex were mostly lower with beans down $.12-$.14 making new lows late. Product pricing flipped from early trade with meal down $3-$5 while oil was steady to 10 points higher. Nov-26 beans traded to a 7-week low while also violating support at its 50-day MA. Longer term support is at its 100-day MA, currently $12.24 ½. Dec-26 meal stalled after failing to trade above this week’s high. For now, Dec-26 oil rejected trade below its Sept-26 low. Crush margins were up $.05 at $2.67 ½ bu. The USDA announced flash sales of 330k mt (12 mil. bu.) to China and 283.5k mt (10.4 mil. bu.) to an unknown buyer. I’d estimate Chinese purchases have reached 15.5-16 mmt. Conab is forecasting Brazil’s 2026/27 production at 181.6 mmt vs. 180.4 mmt in 2025/26. They expect exports in 2026/27 will reach 118 mmt, up from 116.2 in 2025/26. The USDA is forecasting 2026/27 production at 186 mmt with exports also at 118 mmt. NOPA members crushed only 196.3 mil. bu. of soybeans in Sept-26, down from 205.5 mil. in Aug-26 while also below the 197.9 mil. in Sept-25. This was the lowest number of soybeans processed in 13 months and well below expectations of 203.7 mil. Processors took extended down time for maintenance and in some cases due to the lack of soybeans driven by harvest delays. Crush in Iowa, top processing state, was down 13.2% YOY. NOPA data would suggest census crush at 201 mil. bu. the lowest since July-25. Crush will need to Ave. 234.5 mil. bu. per month Oct-26 through Aug-27 to reach the USDA forecast of 2.780 bil. bu. Oil stocks fell to only 1.053 bil. lbs. down 12.3% from the end of Aug-26 and the lowest since Nov-14. Tomorrow’s export sales are expected to range from 18-44 mil. bu. of beans, 200-450k tons of meal and 0-10k tons of oil.
Spillover pressure from lower trade in corn and the soybean complex weighed on wheat prices late, closing $.02-$.04 lower. CGO Dec-26 was down $.03 ¼ at $6.70 after its rally attempt stalled at this week’s high of $6.81. Dec-26 KC was $.02 lower at $7.13, also stalling below this week’s high. Dec-26 MIAX was off $.04 at $6.86 in 2-sided trade. So far the US has just been a bystander as limited supplies from Black Sea region are getting distributed to other global exporters. Wheat offers from ports in Romania and Bulgaria jumped to 3-year highs as Russian drone attacks have damaged or sunk vessels in their coastal waters. Russia claims that they can fully cover Egypt’s demand for grain despite the blockage of the Black Sea supply routes. SovEcon is forecasting Russian wheat exports in Oct-26 at 2.5 mmt, down from 2.6 mmt in Sept-26 while well below the 5.4 mmt in Oct-25. US WW acres in drought held steady at 53%, while spring wheat acres in drought fell 1% to 38%. Tomorrow’s export sales are expected to range from 10-20 mil. bu.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.