Written Commentary

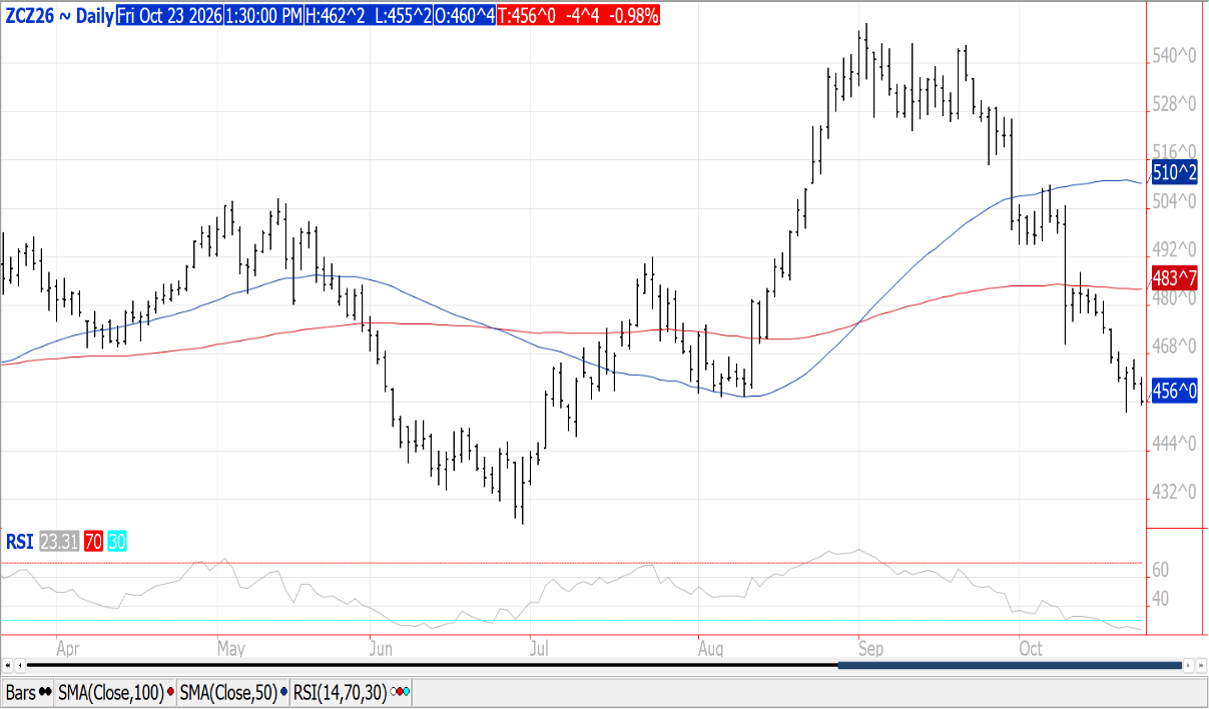
Prices were $.03-$.05 lower while spreads also weakened. Dec-26 held support above this week’s low at $4.53 ½. I expect harvest will likely be 60% complete by the end of this weekend. Prices struggle to find a bottom with harvest pressure while speculative traders continue to shed length. Open interest from yesterday was down 10k contracts. While exports are down 34% YTD vs. the USDA forecast of down 4%, the USDA did announce a flash sale of 116k mt of corn to an unknown buyer. South American production forecasts for the 26/27 MY are considerably higher than the USDA. To form a meaningful price bounce, we’ll need to see a stronger recovery in demand and/or more threatening forecast in South America. The recent low for Mch-27 corn at $4.68 ¼ fits good as a potential low for Q4 given the Oct-26 USDA stocks/use at 11.3%. Cattle on feed as of Oct. 1st at 11.372 mil. head were slightly below YA at 11.418 mil. and below expectations of 11.441 mil. Placements were down 12% vs. expectations of down 8.3%. Marketing were off 7%, in line with expectations.
Prices were mixed and little changed with beans $.03-$.05 higher, meal was mixed while oil was up 10-20 points. Spreads weakened across the complex. Today’s recovery in Nov-26 beans stalled just shy of this week’s high at $12.65. Spot futures ended its run on consecutive lower closes at 8 yesterday while closing slightly higher, this as China continues its march towards acquiring 25 mmt of US beans. Support below the market for Nov-26 beans is at $12.28. Crush margins were down $.05 at $2.40 bu., pulling back to a 5-week low. Dry across the nation’s midsection yesterday. Rain this weekend in the plains and portions of the WCB to stretch into the NC Midwest by early next week. The central Midwest and ECB remain dry enabling US harvest to get back on track. Harvest delays will likely be limited to NE and SE SD. Soybean O.I. plunged just over 26k contracts yesterday as traders unwind positions in Nov-26 futures ahead of FND late next week. Meal O.I. was down 5.6k while oil was down 3.4k contracts. I’d estimate with Chinese purchases have reached 18 mmt. China’s Sinograin will auction off another 512k mt of soybeans from Govt. reserves next Tues. the 27th. US harvest will likely reach 80%+ by the end of this weekend. History would suggest further downside potential for Jan-27 beans with the recent low of $12.50 vs. the Oct-26 stocks/use ratio at 6.9%.
Prices finished steady to slightly lower, unable to hold intraday strength. Spot contracts in all 3 classes were down $.35+ for the week. Hopes for peace in the Black Sea combined with wheat trying to find a price that attracts demand has pressured prices to fresh 3-month lows this week. Both CGO and KC spot futures have fallen more than $1.75 from their respective Sept-26 highs. We’ve got the MM short position in CGO wheat back up to 50k contracts, the largest in 3 months, while nearing flat in KC and MIAX. O.I. in CGO was up 1.5k contracts yesterday while up 1.7k in KC. Trilateral talks between US, Russia and Ukraine are slated for Nov. 10th, meanwhile the fighting continues. US exports are down 33% YOY vs. the USDA forecast of down 17%. Commitments at only 392 mil. bu. are the 2nd lowest in decades. US winter wheat acres in drought slipped 4% this week to 49%.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.