Written Commentary

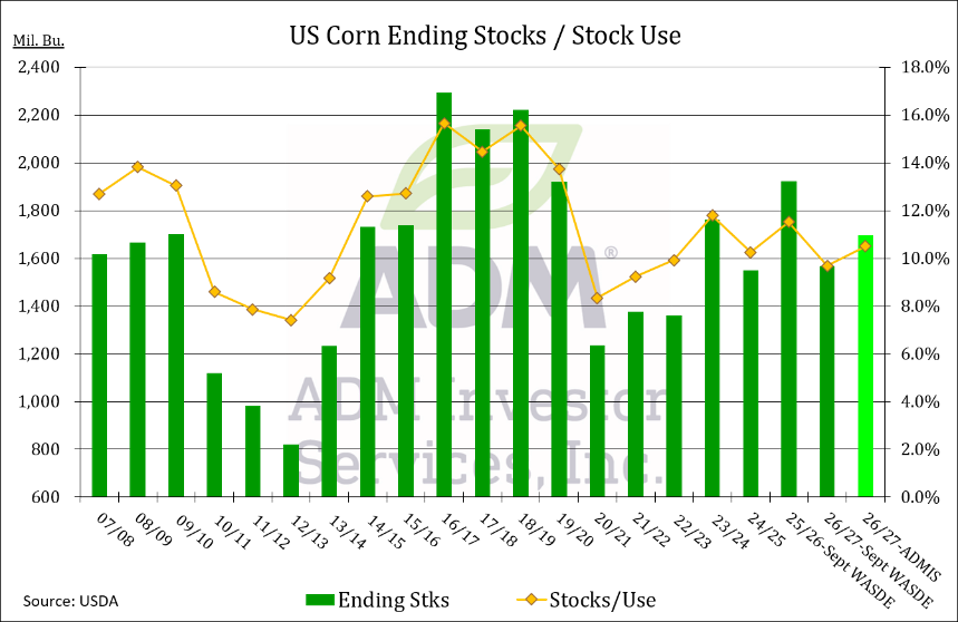
Prices were $.01-$.02 lower while spreads firmed into the close. Dec-26 has support below the market at $4.88 with resistance at this week’s high at $5.09 ¾. Open interest jumped by nearly 10k contracts yesterday after speculative traders sold nearly 13k contracts. The Reuter’s poll shows analysts expect US production will slip roughly 80 mil. bu. to 15.721 bil. bu. with stocks at 1.670 bil., very much in line with our estimates of production at 15.710 bil. and stocks at 1.695 bil. Export sales at 30 mil. bu. were at the low end of expectations. YTD commitments are down 34% from YA vs. the USDA forecast of down 4%. Commitments represent 23.5% of the USDA est. vs. the historical average of 32.5%. Despite the slow pace to date, I do not look for the USDA to make any changes this month with demand potential to China and the presence of “Super El Nino.” It’s been 16 years since we’ve seen a production change of more than 200 mil. bu. in the October USDA report. Production was down nearly 500 mil. bu. in 2010, while up just over 650 mil. in 2004.
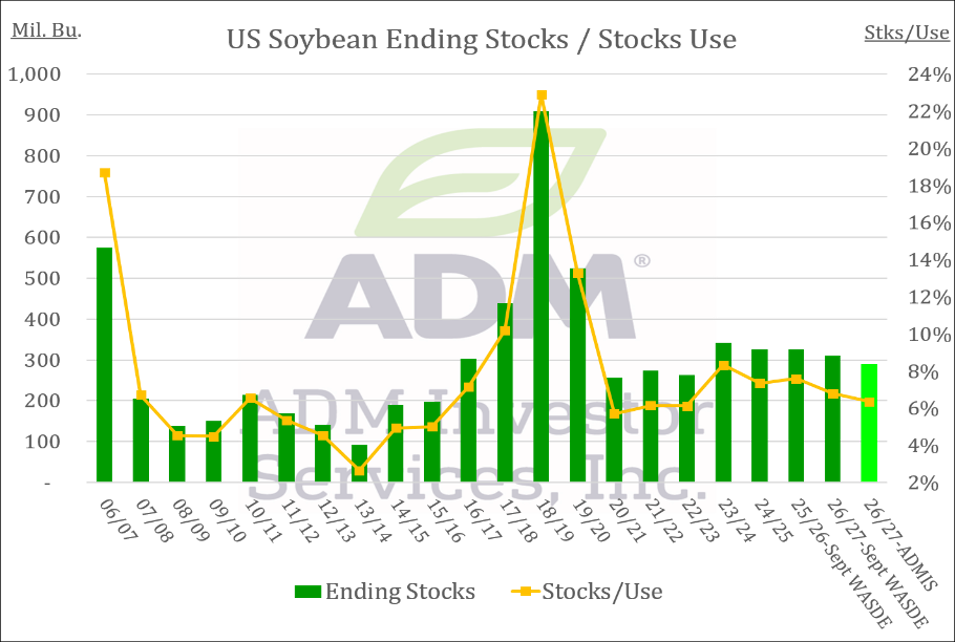
Prices across the complex were mixed with beans down $.10 closing near session lows, meal was off $6-$8 while oil was 15-20 points higher. Spreads were mixed all around. Nov-26 beans have support just below $12.75 with resistance at the contract high at $13.35 ¼. Dec-26 meal rejected trade above yesterday’s high while falling back to the midpoint of its 2-week range. Support for Dec-26 oil is at 66.61. Isaias reached hurricane status overnight and is expected to make landfall near the Florida/Alabama border Friday night or Sat. AM as a Category 2 storm. Damaging winds and coastal flooding are expected; however minimal impact is expected for Gulf export operations. Harvest activity in the SE and ECB will be slowed while favorable harvest conditions in the central and WCB are expected to last into the middle of next week. The Reuter’s poll shows the Ave. production estimate at 4.534 bil. bu. with stocks at 305 mil. just above our expectations of production at 4.510 bil. and stocks at 290 mil. US Gulf FOB offers remain $.10-$.20 below Brazilian offers through the end of the year. By Jan-27 Brazilian offers are $.80-$.90 below US. Export sales at 20 mil. were below expectations. YTD commitments are up 80% from YA vs. the USDA forecast of up 11%. While Chinese purchases were reported at 383k mt, new sales were virtually zero as 370k mt were switched from unknown. Known Chinese commitments are at 11.142 mmt with another 5.717 mmt to unknown. I’d estimate total Chinese purchases just under 15 mmt. Old crop meal commitments were up 16% YOY vs. the USDA forecast of up 13%. Old crop oil sales at 828 mil. lbs. are down 66% vs. the USDA forecast of down 61%. Look for some bean oil export demand to be shifted to usage for green diesel production in tomorrow’s WASDE report.
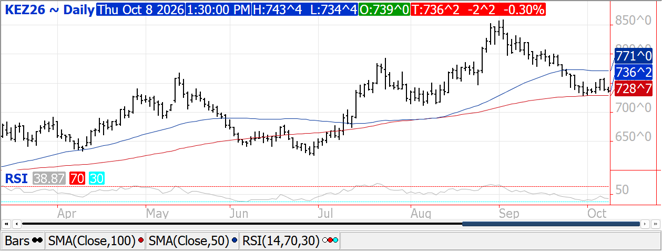
Prices closed slightly lower across the 3 classes in 2-sided trade. CGO Dec-26 was down $.03 ¼ at $6.83 ¼, Dec-26 KC was $.02 ¼ lower at $7.36 ¼, while Dec-26 MIAX is off $.04 ¼ at $7.06. Little to no response from NATO following reports Russia struck vessels in the Black Sea off coastal waters of Bulgaria and Romania this week. SovEcon lowered their Russian production forecast nearly 1% to 87.5 mmt, vs. the USDA est. of 88 mmt. Lithuania is looking to prohibit the transport of Russian grain through their country to Baltic Sea ports. Open interest rose 2.7k contracts in CGO while up 2.4k in KC. The Rueter’s poll shows traders expect 2026/27 US wheat stocks to rise only 4 mil. bu. to 721 mil. vs. our estimate of 735 mil. as I look for the USDA to start lowering exports. Export sales at 17 mil. bu. were a 4-month high. YTD commitments are down 32% from YA vs. the USDA forecast of down 15%. Sales represent 48% of the USDA forecast, vs. the historical average of 56%. US winter wheat areas in drought dropped 4% to 53% while spring wheat in drought fell 9% to 39%.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 2547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2021 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.